Ascend Loans Pros and Cons You Should Know Before Applying
If you searched "Ascend Loans," there's a good chance you landed on results for three different companies before finding this one. That mix-up matters, because the terms are nowhere close to each other. This review covers Ascend Loans, LLC — the tribal lender behind ascendloans.com — not Ascend Consumer Finance's personal loan product or Ascend Debt Relief's settlement service. We'll clear up that confusion first, then walk through exactly what you're signing up for.
Quick Answer: Is Ascend Loans a Good Idea?
Ascend Loans can get you $300 to $2,000 in your account within a day, even with poor credit, no credit history, or past loan defaults. That speed and accessibility come at a steep cost: this is a short-term, tribal-lending product, which means it isn't bound by most state interest rate caps. If you can pay it back in one or two cycles for a genuine emergency, it may serve its purpose. If you're likely to need several months to repay, the cost structure works against you, and you should rule out cheaper options first.
Which "Ascend" Are You Looking At?
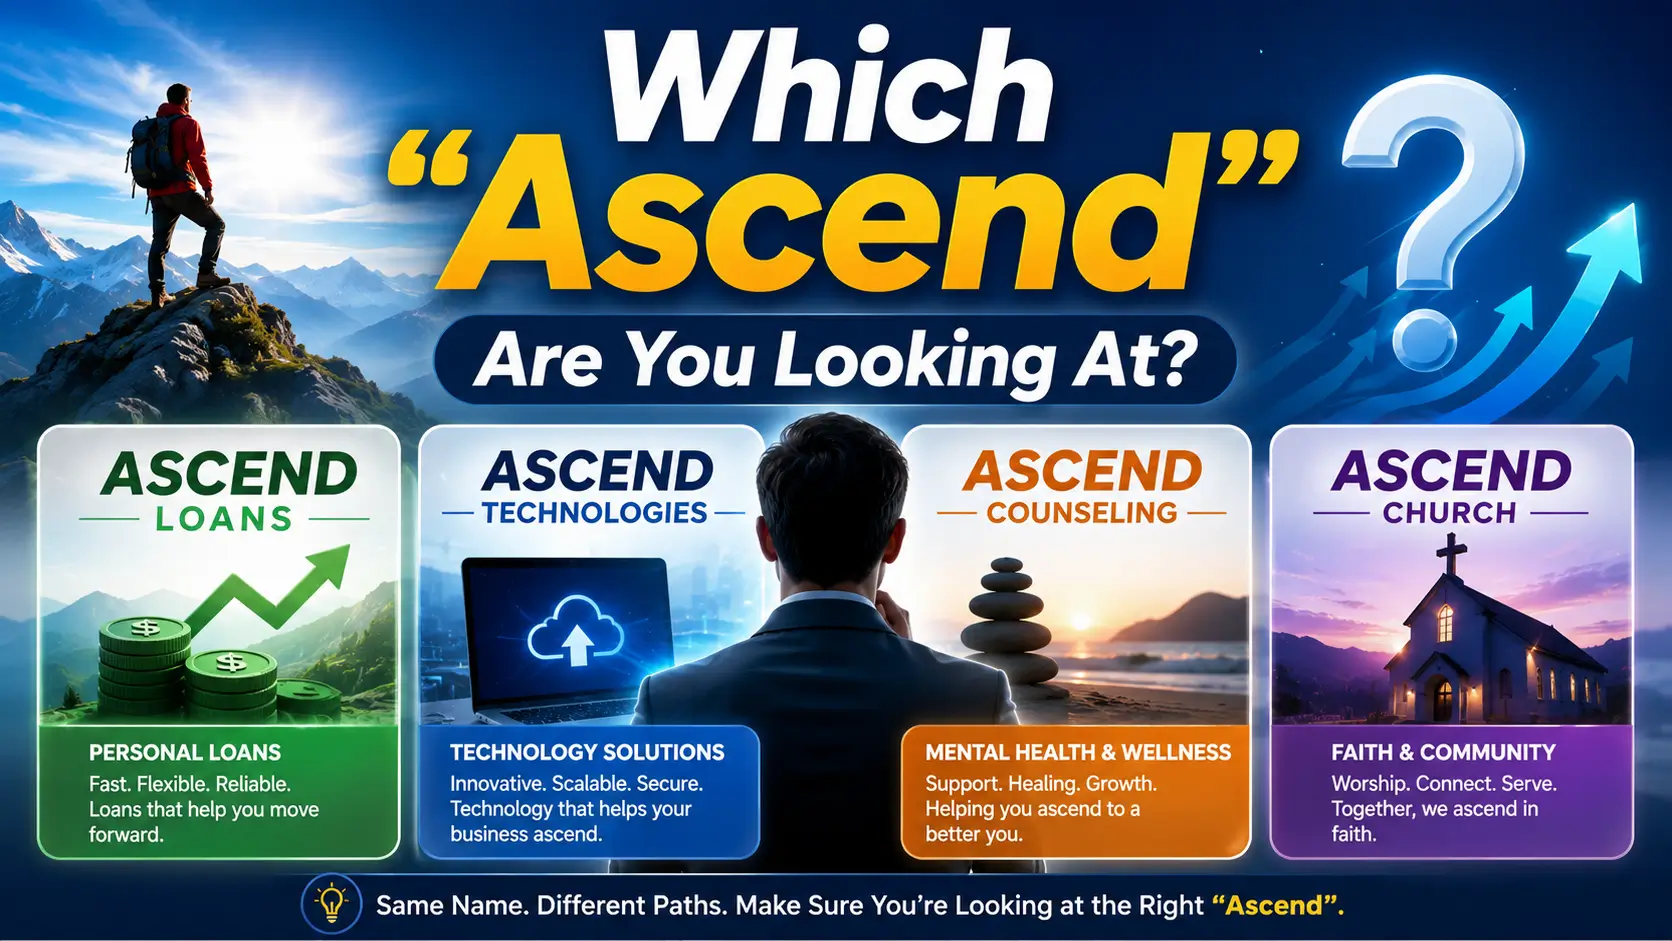
This confusion shows up constantly in search results, so it's worth 30 seconds to sort out:
| Company | What it actually is | Typical cost |
|---|---|---|
| Ascend Loans, LLC (ascendloans.com) — this review | Tribal short-term installment lender, owned by the Habematolel Pomo of Upper Lake | High APR, not capped by state law |
| Ascend Consumer Finance ("Ascend Personal Loans") | San Francisco-based direct lender, larger installment loans | APR roughly in the high-20s to mid-30s |
| Ascend Debt Relief | Debt settlement company, not a lender | Fee-based, no loans issued |
| Ascent (no "d") | Private student loan lender | Unrelated business entirely |
If a competitor's review swaps in APR numbers or fee structures from one of these other companies, that's a sign it wasn't fact-checked against the actual lender — and it's the single most common accuracy gap in existing coverage of this topic.
What Ascend Loans Actually Offers
Ascend Loans, LLC operates as an economic development arm of the Habematolel Pomo of Upper Lake, a federally recognized tribe. Because the loans are issued and regulated under the tribe's own financial services code rather than state consumer lending law, Ascend isn't subject to the interest rate caps that apply to most storefront and online lenders operating under state licenses. That single fact explains almost everything else about the pros and cons below.
The basics:
- Loan amounts: $300–$1,200 for first-time borrowers; up to $2,000 for repeat customers in good standing
- Funding speed: as fast as ~30 minutes after signing for instant funding, or next business day via standard ACH
- Credit check: soft and alternative-data checks are used; a low credit score alone won't automatically disqualify you
- Repayment: fixed installment schedule, not a single lump-sum payday-loan structure
- Rewards tiers: repeat borrowers can move from the "Emerald Trek" tier to "Emerald Ascent," unlocking lower rates and higher loan amounts over time
Pros of Ascend Loans
1. Accessible to subprime and no-credit-history borrowers. Ascend evaluates alternative data alongside traditional credit bureaus, so a thin or damaged credit file doesn't automatically mean a decline.
2. Genuinely fast funding. Instant-funding approvals can land in your account in around 30 minutes; standard approvals typically fund the next business day.
3. Installment structure, not a payday lump sum. You repay in scheduled installments rather than one balloon payment, which is easier to budget around than a traditional payday loan.
4. No prepayment penalty. Paying the loan off early doesn't trigger an extra fee, so you can cut your total interest cost if your cash flow improves.
5. Auto-Pay discount available. Enrolling in automatic payments can meaningfully lower your rate compared to manual repayment, on top of making it harder to miss a due date.
6. Soft-pull rate check. You can see estimated terms through Instant Bank Verification without it hitting your credit report the way a full application would.
7. Loyalty pricing for repeat borrowers. Successfully repaying a loan and moving up reward tiers unlocks larger amounts and better pricing on future loans — an incentive structure most single-loan subprime lenders don't offer.
Cons of Ascend Loans
1. Interest rates are very high. Independent review sites and customer-reported figures put effective APRs in the multiple-hundred-percent range for standard borrowers — several times higher than even most subprime personal loan alternatives. Ascend's own site doesn't publish a flat APR figure (it varies by loan agreement and state of access), so treat any specific number you see online, including in this space, as an estimate to verify against your actual loan agreement before signing.
2. Tribal lending model limits your legal protections. Because the loan is issued under tribal law rather than your state's consumer lending statutes, state interest rate caps and some consumer protections that would normally apply to a loan in your state don't govern this agreement.
3. Small loan ceiling. At $300–$1,200 for new borrowers (up to $2,000 with a track record), this isn't a fit for anything beyond a short-term cash gap.
4. Late fees apply. Missing a scheduled payment can add a fee on top of an already high-cost loan.
5. Not a fit for ongoing or large expenses. This product is explicitly positioned by the lender as expensive, short-term credit — not a long-term financing solution.
6. Limited public accreditation info. Unlike bank-funded or state-licensed lenders, there's less third-party oversight data (BBB accreditation status, state licensing) to independently verify the same way you could for a traditional installment lender.
How the Application Process Works
- Apply online at ascendloans.com with basic personal, employment, and income information.
- Bank verification. Ascend uses Instant Bank Verification (IBV) — a one-time, read-only look at your bank statements to confirm income and account activity. It cannot move money or access funds.
- Review your loan agreement carefully. This document is where the actual APR, fee schedule, and full repayment terms for your specific loan are disclosed — read it before signing, since terms can vary by state of access and individual underwriting.
- Sign electronically. You typically have a window (commonly 24 hours) to review and sign after approval.
- Get funded. Funds are sent via ACH to your checking account — instantly for eligible instant-funding approvals, or the next business day otherwise.
Alternatives Worth Comparing First
Before signing an Ascend Loans agreement, it's worth pricing out lower-cost options for the same emergency need:
- Credit union payday alternative loans (PALs): Federally capped at 28% APR, designed specifically to compete with high-cost short-term lenders.
- A 0% or low-APR credit card cash advance: Even with a cash advance fee, this is often cheaper than a triple-digit APR installment loan if you can repay quickly.
- Nonprofit or employer emergency assistance programs: Many employers and community organizations offer no-interest or low-interest emergency funds that don't show up in typical loan searches.
- A traditional subprime personal loan lender: Companies operating under state lending licenses (rather than tribal jurisdiction) are bound by your state's rate caps, which — even on the high end of subprime pricing — will usually land well below what a tribal short-term lender charges.
The right alternative depends on how much you need, how fast you need it, and how long you'll need to repay — there's no single best option for everyone.
Frequently Asked Questions (FAQs)
Is Ascend Loans the same company as Ascend Personal Loans?
No. Ascend Loans, LLC (ascendloans.com) is a tribal short-term lender. "Ascend Personal Loans" typically refers to Ascend Consumer Finance, a separate, San Francisco-based direct lender with different rates and a different regulatory structure.
Is Ascend Loans legal?
Yes. Ascend Loans, LLC operates under a license from the Habematolel Pomo of Upper Lake's Tribal Financial Services Regulatory Commission, and tribal lending is a recognized legal framework in the U.S. That said, "legal" doesn't mean "regulated the same way as a state-licensed lender" — the interest rate caps and some protections your state law provides for other loans generally don't apply here.
How much can I borrow from Ascend Loans?
First-time borrowers are typically eligible for $300 to $1,200. Returning customers in good standing can qualify for up to $2,000 through the Emerald Rewards tiers.
Does Ascend Loans check my credit?
Ascend uses a combination of traditional credit bureau data and alternative data sources, so applicants with poor or limited credit history can still be considered.
Can I pay off an Ascend loan early without a penalty?
Yes, Ascend Loans does not charge a prepayment penalty, so paying off the balance ahead of schedule can reduce your total interest cost.