Blue Mountain Loans Review: Is It Legit? Rates, Terms & How It Works
If you've landed on Blue Mountain Loans while searching for fast cash with bad credit, here's the short version: it's a real, licensed-by-a-tribe lender — not a scam — but it's also one of the most expensive ways to borrow money in the country, with APRs that can climb past 600%. Before you sign anything, it's worth understanding exactly how that cost adds up and why it's legal in the first place.
Quick verdict
| Legit? | Yes — but it's a tribal lender operating outside most state usury caps |
| APR range | No published minimum; tops out around 660% |
| Loan amount | $100–$1,200 |
| Repayment term | 4–12 months |
| Credit check | Soft pull; bad credit and past bankruptcy accepted |
| Funding speed | As soon as the same day, next business day at the latest |
| BBB rating | F (not accredited) |
| Best for | Borrowers who have exhausted every other option and understand the true cost |
Is Blue Mountain Loans legit?
Yes. Blue Mountain Loans is a real, operating lender — it's a d/b/a of Loan Spot, which is owned and operated by the Kashia Band of Pomo Indians of the Stewarts Point Rancheria, a federally recognized tribe based in California. That tribal ownership is the whole story here, so it's worth unpacking rather than glossing over.
How tribal lending actually works (and why the rates are so high)
Tribes have sovereign immunity, meaning tribal businesses generally aren't bound by individual state lending laws — including interest rate caps. A lender operating under that structure can charge rates that would be illegal if a bank or a non-tribal payday lender charged them in the same state.
That's the legal mechanism. It's also the center of ongoing controversy known informally as "rent-a-tribe" lending: consumer attorneys allege that in many of these arrangements, a non-tribal company handles the marketing, underwriting, funding, and collections, while the tribal entity is largely a name on the paperwork that provides legal cover from state regulation. Whether that applies to any specific lender is a legal question decided case by case — but it's the reason tribal lending draws so much legal scrutiny.
As of 2026, the consumer law firm Kelly Guzzo, PLC is actively investigating Loan Spot d/b/a Blue Mountain Loans, alleging the company has issued loans with interest rates exceeding 500% — rates that would violate usury laws in every state, since even permissive states rarely allow more than 36% APR on small loans, and states like Virginia (12%) and California (10%, absent an exemption) cap rates far lower. No court has ruled against the company as of this writing, and an investigation is not a finding of wrongdoing — but it's a material fact worth knowing before you sign a loan agreement, and one most reviews of this lender leave out entirely.
BBB standing
Blue Mountain Loans is not BBB accredited and holds an F rating. The current BBB profile shows the business has failed to respond to 27 of 29 total complaints filed against it, and its customer review average sits at 1 out of 5 stars. Recurring themes in complaints:
- Interest rates so high that biweekly payments barely touch the principal
- Difficulty getting a straight answer on payoff amounts
- Approval followed by unexplained denial after underwriting
- Disputes over whether the loan is even legal in the borrower's home state
How Blue Mountain Loans works
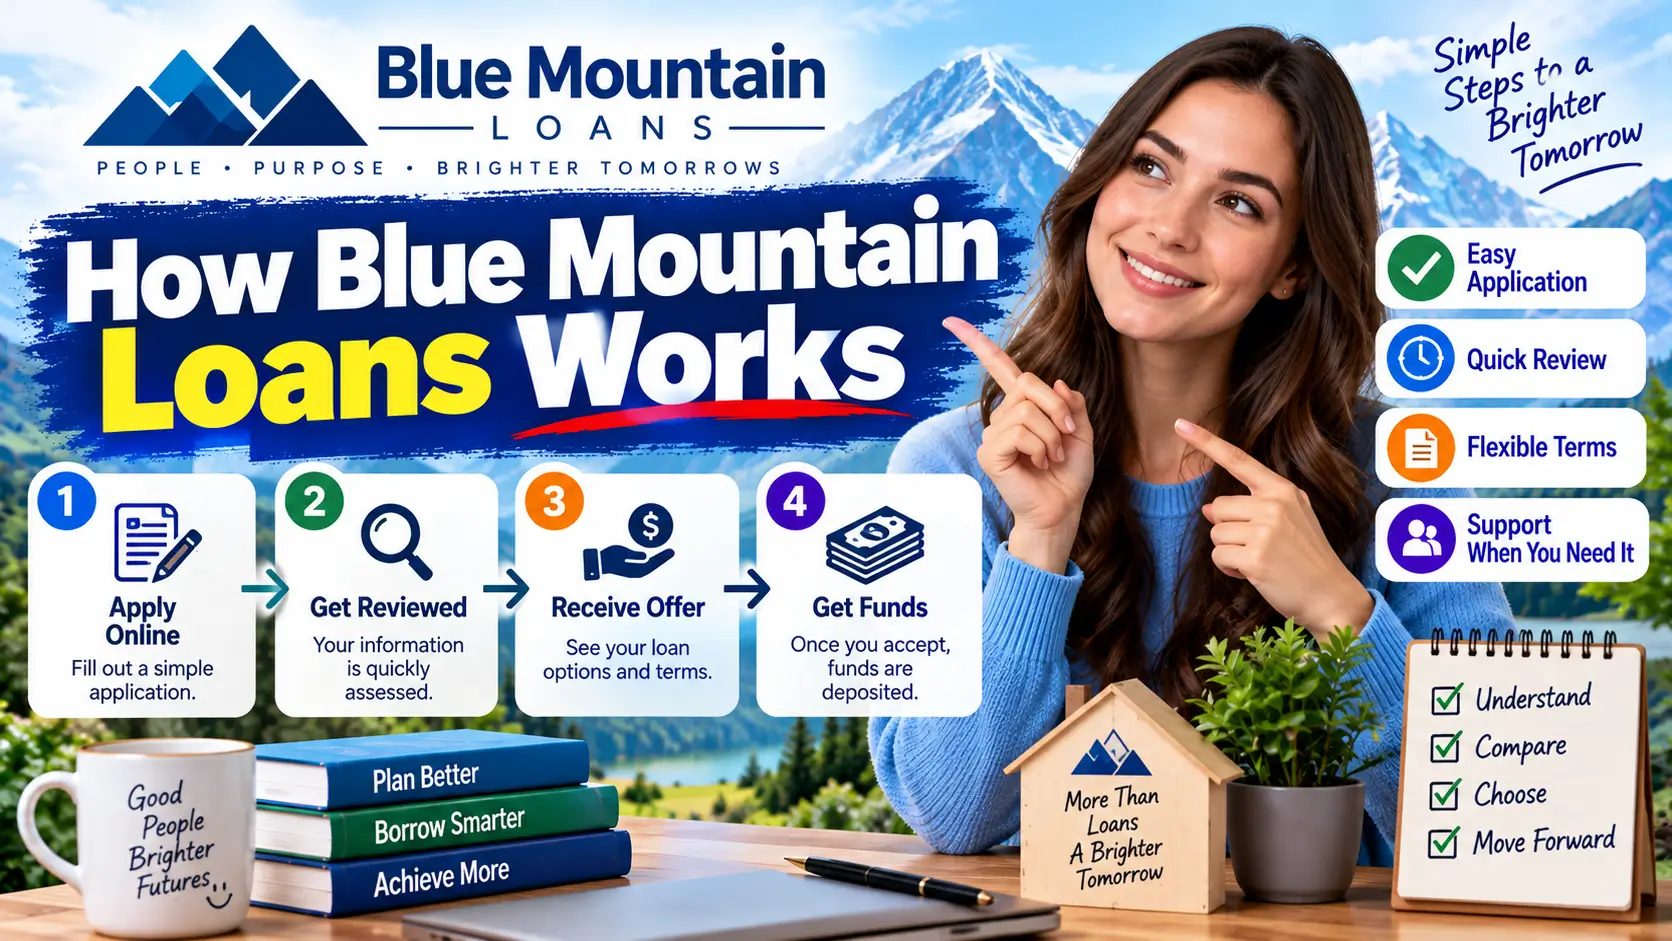
- Apply online. You'll provide personal, banking, and employment details and request a loan amount. This usually involves a soft credit check, not a hard pull.
- Speak with a representative. If preliminarily approved, someone calls to walk through terms before you commit.
- Review the loan agreement. This is the step to slow down on — read the APR, total repayment amount, and payment schedule line by line before signing.
- Get funded. Money is typically deposited the same day or by the next business day.
- Repay on schedule. Payments are automatically withdrawn weekly, biweekly, semi-monthly, or monthly depending on your agreement.
Eligibility requirements
- 18 years or older
- U.S. citizen or permanent resident
- Active checking account in your name
- Verifiable, steady income
- No minimum credit score — bad credit and past bankruptcy are both accepted
Rates, terms, and what a loan actually costs
| Detail | Blue Mountain Loans |
|---|---|
| Loan amount | $100 – $1,200 |
| APR | Not disclosed as a minimum; up to 660% |
| Term length | 4 – 12 months |
| Origination fee | May apply (not published as a flat rate) |
| Late payment fee | May apply |
| Returned payment fee | $30 |
| Prepayment penalty | None |
Because Blue Mountain Loans doesn't publish a minimum APR, you won't know your real rate until you're underwritten — which means you can't comparison-shop before applying. That's a meaningful gap for readers trying to decide whether it's worth applying at all.
What a triple-digit APR actually does to your payments
Loan math at these rates behaves very differently than a typical personal loan. A real complaint filed with the BBB in 2026 illustrates it well: a borrower took an $800 loan and, after paying $1,742.66 across roughly ten months of payments, still hadn't retired the debt. At a 470% APR on another $800 loan, a second complainant had paid $453 within about six weeks and still owed more than the original $800 borrowed. The pattern in both cases is the same — early payments are consumed almost entirely by interest, so the principal barely moves even after months of on-time payments.
If you're evaluating whether you can afford a loan like this, run the numbers past the sales pitch: ask the representative for the total repayment amount in dollars, not just the APR percentage, and compare it to what you're actually borrowing.
Where it's not available
Blue Mountain Loans doesn't lend to residents of: Arkansas, Connecticut, Illinois, Maryland, Massachusetts, New York, Pennsylvania, Vermont, Virginia, and West Virginia — all states with stricter interest rate caps or specific prohibitions on this loan structure. If your state isn't on that list, that doesn't mean the loan is inexpensive; it means your state hasn't blocked tribal lenders from operating there.
Pros and cons
Pros
- No minimum credit score; bankruptcy history doesn't disqualify you
- Fast approval decision and same- or next-day funding
- No prepayment penalty if you can pay it off early
- Simple online application
Cons
- APRs up to 660% — among the highest of any legal lender
- No published starting APR, so you can't rate-shop before applying
- F rating with the BBB and a high volume of unresolved complaints
- Small loan amounts ($1,200 max) don't solve larger financial gaps
- Subject of an active consumer-law investigation into rates exceeding state usury limits
- Loan not available in 10 states
Alternatives worth comparing first
Before accepting a Blue Mountain Loans offer, it's worth getting at least one comparison quote. A few paths that typically cost less:
- Installment lenders with bank partnerships (e.g., OppLoans) generally cap APR in the 129%–195% range — still expensive, but meaningfully lower, and loans are larger.
- Cash advance apps (e.g., EarnIn, Chime MyPay, Varo Advance) let you access a portion of pay already earned, often for a flat fee instead of an APR, if you have qualifying direct deposits.
- Credit union payday alternative loans (PALs) are federally capped at 28% APR for amounts up to $2,000 — the closest like-for-like replacement if you have or can open a credit union membership.
- Local nonprofit and hardship funds, community action agencies, or employer-based emergency advance programs are worth ten minutes of research before any triple-digit-APR loan.
Red flags to check before you sign
Because Blue Mountain Loans doesn't publish a fixed rate sheet, the terms you're offered depend on underwriting — which means two borrowers with similar credit can walk away with very different costs. Before signing, confirm these four things in writing:
- The exact APR and total repayment amount in dollars, not just the payment schedule. A representative quoting "$X every two weeks" without the total is not giving you enough information to decide.
- Whether your state is on the excluded list. If Blue Mountain Loans isn't licensed to lend in your state, that's worth flagging with your state attorney general's consumer protection office — several BBB complainants report doing exactly this.
- What happens if you miss a payment. Ask specifically about the $30 returned payment fee, late fees, and whether a missed payment resets your progress toward payoff.
- Whether the balance is reported to credit bureaus, and under what circumstances (some BBB complaints describe balances being reported even after account closure).
None of this makes the loan cheaper, but it prevents the most common complaint pattern seen in BBB filings: borrowers who didn't realize how little of each payment was reducing their principal until they were several months in.
Frequently Asked Questions (FAQs)
Is Blue Mountain Loans a scam?
No. It's a licensed tribal lending business that funds real loans. "Legitimate" and "affordable" aren't the same thing here, though — the rates are legal but extremely high.
Why can Blue Mountain Loans charge such high interest rates?
As a business owned by a federally recognized tribe, it operates under tribal sovereign immunity rather than individual state usury laws, which is why its rates can exceed caps that apply to state-licensed lenders.
What credit score do I need?
There's no published minimum. The company markets specifically to borrowers with bad credit or past bankruptcies, basing approval mainly on income and banking history.
Can I pay off my loan early to save on interest?
Yes — Blue Mountain Loans doesn't charge a prepayment penalty, so paying ahead of schedule reduces the total interest you pay.
Is there a class action lawsuit against Blue Mountain Loans?
As of 2026, at least one consumer law firm (Kelly Guzzo, PLC) has publicly announced it is investigating the company over rates it alleges exceed state usury limits. This is an active investigation, not a finalized lawsuit or court judgment, so treat it as a factor to watch rather than a settled outcome.
Bottom line
Blue Mountain Loans is legitimate, fast, and genuinely accessible if your credit has closed every other door. But "accessible" comes at a steep price — a 660% APR ceiling, an F BBB rating, and an open legal investigation into whether its rates even comply with the law in borrowers' home states. If you're considering it, request the total repayment dollar amount before signing, confirm your state allows the loan, and get at least one lower-cost quote first.