Is Greenline Loans Right for You? Here's What Borrowers Should Know
If you're searching for "Greenline Loans review," you're probably staring down an emergency expense and wondering if this is a safe way to get cash fast. Here's the short version: Greenline Loans is a tribal lender, which changes the rules in ways most comparison sites gloss over. Before you apply, you need to understand what that means for your interest rate, your legal protections, and your total repayment cost.
This guide breaks down exactly who operates Greenline Loans, what it actually costs, the legal history you won't find on their own site, and which alternatives are worth checking first.
What Is Greenline Loans?
Greenline Loans is an online lending brand operated by Waawaatesi LLC, doing business as Greenline Loans. Waawaatesi LLC is owned by the Lac du Flambeau Band of Lake Superior Chippewa Indians, a federally recognized tribe based in Wisconsin. The company operates as a tribal lender, meaning it lends under tribal sovereign immunity rather than under a state lending license.
That distinction matters more than almost anything else in this review, so it's worth explaining before we get to rates and terms.
What "Tribal Lender" Actually Means for You
Tribal sovereign immunity generally shields tribally-owned lenders from state usury laws — the laws that cap how much interest a lender can charge. That's the entire business model: it lets Greenline Loans charge rates that would be illegal for a state-licensed lender in most states, and lend into states where payday-style lending is otherwise restricted or banned (including New York, Pennsylvania, and Connecticut, depending on current state-by-state availability).
The trade-off for borrowers is real:
- Limited legal recourse. Disputes are generally governed by tribal law, not your state's consumer protection statutes, and you typically can't sue in state court.
- The CFPB's authority is limited over tribally-affiliated lenders compared to state-licensed ones.
- You're waiving protections you'd otherwise have with a bank, credit union, or state-licensed installment lender.
This isn't unique to Greenline — it's how every tribal lender operates. But it's the single most important thing to understand before you apply, and it's exactly why we're leading with it instead of the interest rate.
How Greenline Loans Works
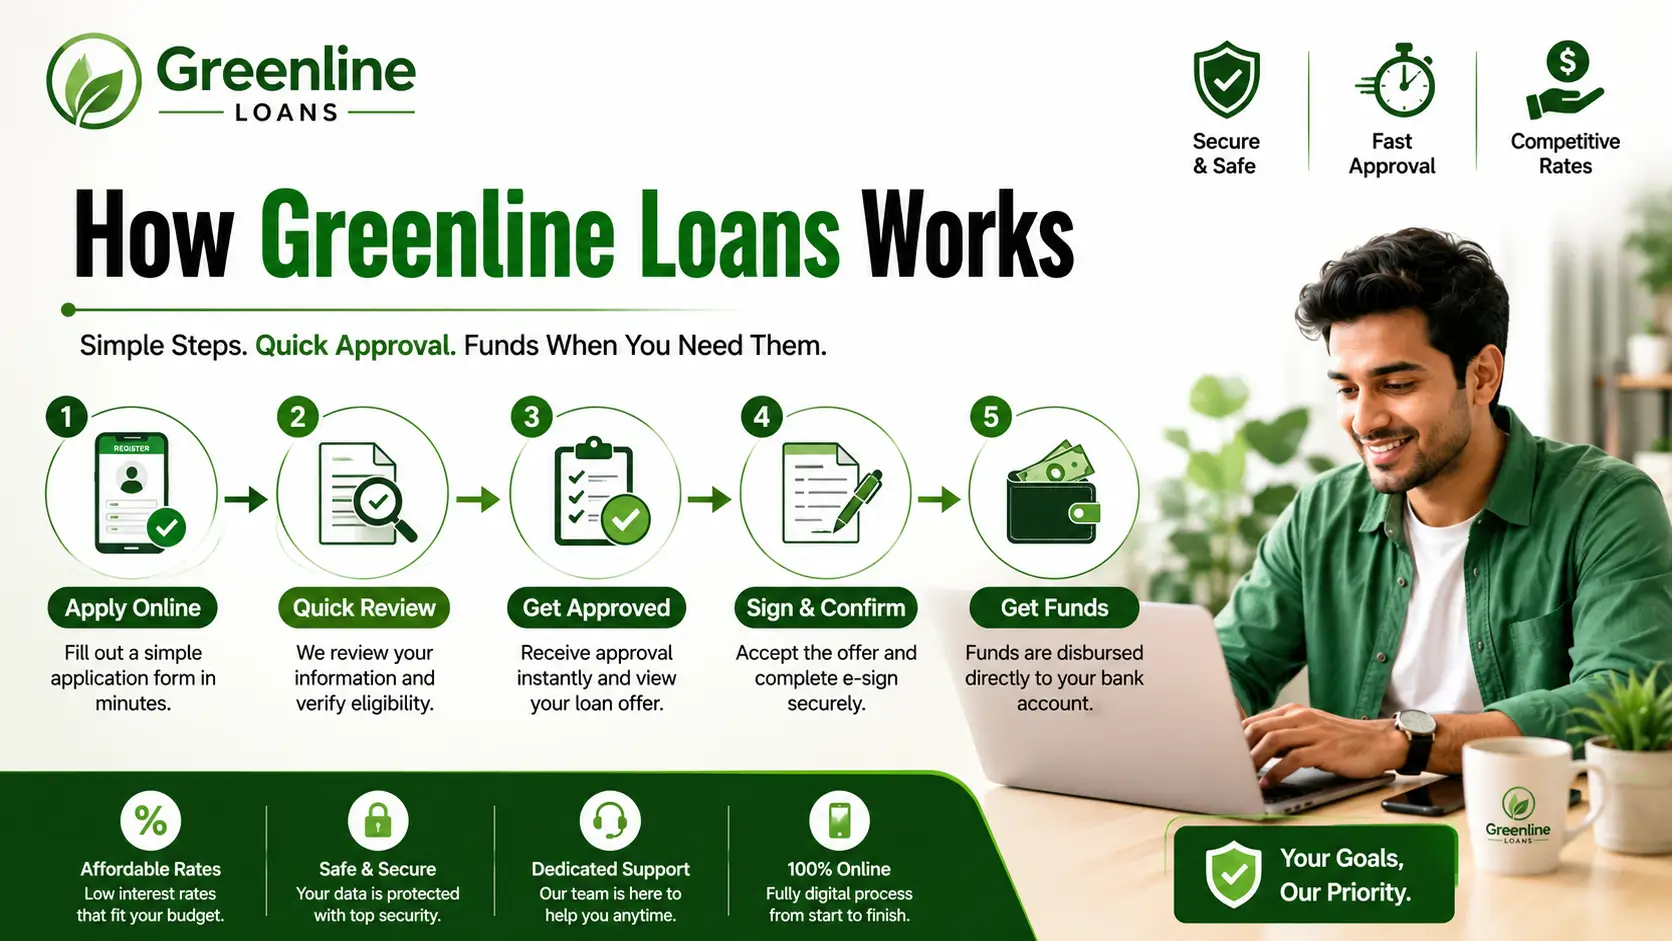
Greenline Loans markets itself to borrowers with poor or no credit who need cash quickly, typically for emergencies like car repairs, medical bills, or bridging a gap between paychecks.
- Loan amounts: Reported figures vary by source and have changed over time — some describe an initial loan around $300 with repeat-borrower installment loans up to $1,000, while other listings describe a revolving line of credit up to $2,500. Treat any amount you see quoted online as unconfirmed until it appears in your actual loan agreement.
- Loan type: Short-term installment loan or line of credit, not a traditional lump-sum payday loan.
- Credit check: No hard credit pull is typically required, so applying shouldn't affect your credit score — approval is based on other factors like income and banking history instead.
- Funding speed: Same-day or next-business-day funding is commonly advertised.
- Application: Fully online, and Greenline states loans can't be renewed or extended, though late fees may apply if a payment is missed.
We were not able to pull a current, verified rate table directly from Greenline's live site during this review (their rates and terms page did not load through automated access). If you're evaluating an offer, request the full APR and fee schedule in writing before signing — don't rely on any number you read on a third-party site, including this one.
The Real Cost: APR and Fees
This is where Greenline Loans separates itself from most personal loan options, and where a lot of borrowers get caught off guard.
Multiple independent reviews and consumer complaints put Greenline's APR in the 300%–700%+ range, with some individual complaints citing effective APRs above 800% once fees are included. One frequently cited historical sample loan showed a $300 loan generating over $630 in interest alone before it was paid off — more than double the original amount borrowed.
Beyond the headline APR, watch for:
- Monthly maintenance fees, charged whether or not you actively borrow against your line
- Per-draw transaction fees each time you pull funds
- Late fees if a payment is missed
Deferred interest note: Greenline Loans is not a deferred-interest or promotional-APR product — interest accrues from day one at the full rate. There's no "pay it off in X months to avoid interest" period to plan around, so the total cost is essentially locked in from the moment you borrow.
Because APR and fee structures on tribal lending products change without much public notice, treat every figure above as directional, not a quote. Confirm the exact numbers in your personalized loan agreement.
Legal History You Should Know About
Most Greenline Loans content online is either the company's own marketing copy or a generic rate comparison. Neither tends to mention this:
- In 2024, Greenline Loans (through Waawaatesi LLC) was named in a proposed class action lawsuit (Spurr v. Greenline Loans) alleging a "rent-a-tribe" scheme — the suit claimed the lending operation was effectively run by non-tribal parties using tribal affiliation to sidestep state usury laws, and that it issued illegal high-interest loans to residents of states like Illinois where such rates aren't permitted.
- Greenline Loans was also named among a group of related lending brands — including Quick Help Loans, Loan At Last, Lakeshore Loans, and Cash Aisle — in a broader 2024 settlement covering certain internet loans issued under this network of names.
- Public BBB complaint records include multiple borrowers disputing effective interest rates in the 700%–800%+ range and describing confusion over which specific lending entity they were actually borrowing from, since the operating brand names have shifted over time (Greenline Loans, Quick Help Loans, and others appear connected).
None of this means every loan issued was unlawful, and litigation outcomes can change. But if a lawsuit alleging your lender misrepresented its tribal status is public record, that's information you deserve before you sign anything — not after.
Who Can (and Can't) Borrow
Greenline Loans does not lend in every state. State exclusion lists reported across sources include (at various points) Arkansas, Colorado, Connecticut, Georgia, Illinois, Maryland, Massachusetts, Minnesota, Montana, New Hampshire, New Mexico, New York, North Carolina, Pennsylvania, South Carolina, Vermont, Virginia, Washington, West Virginia, and Wisconsin — though this list has changed over time and litigation may affect current availability in some states. Confirm your state's eligibility directly on Greenline's application before assuming you qualify.
Beyond location, expect general requirements like:
- Regular income (employment or benefits)
- An active checking account for direct deposit and repayment
- Being of legal borrowing age in your state
Greenline Loans: Pros and Cons
What might appeal to borrowers:
- No hard credit check, so applying doesn't ding your credit score
- Accepts very poor or thin credit files
- Fast, fully online application and funding
- Available in some states where traditional payday lending is restricted
What should give you pause:
- APR potentially in the 300%–700%+ range — among the highest of any legal lending category
- Tribal sovereign immunity limits your legal recourse if something goes wrong
- Ongoing/monthly fees even when you're not actively borrowing, depending on the product structure
- Named in a 2024 class action alleging misrepresentation of its tribal-lending structure
- Rate and fee transparency on the live site is inconsistent — get everything in writing
Greenline Loans vs. Alternatives
Before applying, it's worth comparing Greenline against other options for bad-credit borrowers — several of which come with meaningfully lower cost and stronger legal protections.
| Option | Typical APR Range | Credit Check | Legal Protections | Best For |
|---|---|---|---|---|
| Greenline Loans | ~300%–700%+ | No hard pull | Limited (tribal law) | Last resort, small emergency amounts |
| Credit Union PAL (Payday Alternative Loan) | Capped at 28% by federal rule | Soft/light check, membership required | Full state/federal protections | Credit union members needing small, short-term cash |
| State-licensed bad-credit installment lenders (e.g., OppLoans, Possible Finance) | Roughly 100%–200%, varies by state | Soft check common | Full state consumer protections | Borrowers who don't qualify for a credit union but want state oversight |
| 0% APR paycheck advance apps | $0–$14 flat fee typically | None | Standard app terms | Small, short gaps before payday |
| Secured credit card / credit-builder loan | Standard card APR if carried | Soft or hard, varies | Full protections | Borrowers who can wait a few days and want to build credit |
A federal credit union PAL, in particular, is worth checking first if you belong to one (or can join one) — the interest rate is capped by regulation at a fraction of what a tribal lender can legally charge.
Is Greenline Loans Right for You?
Based on what's verifiable about Greenline Loans, it's reasonable for a narrow set of borrowers and risky for most others.
It might make sense if:
- You've exhausted lower-cost options (credit union PAL, 0% apps, family/friends, employer advances) and still need cash today
- You can pay off the loan in full, fast — the total cost compounds quickly the longer it's outstanding
- You've read the actual loan agreement, not just marketing copy, and you're comfortable with the real APR in writing
It's probably not right for you if:
- You have any access to a credit union, a lower-APR bad-credit lender, or a 0% paycheck advance app
- You're not confident you can repay quickly — the effective cost at these rates escalates fast
- You're not comfortable with limited legal recourse if a dispute arises
If you do decide to move forward, request written confirmation of the APR, all fees, and total repayment amount before you sign, and confirm which specific legal entity you're borrowing from — the brand names in this space have shifted before.
Frequently Asked Questions (FAQs)
Is Greenline Loans legit?
Greenline Loans is an operating tribal lending business, not an outright scam — it's a real product from a real company. "Legit" and "affordable" aren't the same thing, though, and the very high APR combined with pending litigation over its lending structure are legitimate reasons for caution.
Will applying to Greenline Loans hurt my credit score?
Reported information indicates approval doesn't typically require a hard credit inquiry, so applying alone shouldn't affect your score. Confirm this in your specific application flow, since policies can change.
Can I get out of a Greenline Loans agreement once I've signed?
Contact Greenline directly about your specific loan terms and repayment options. If you believe you were charged a rate that's illegal in your state, consider contacting your state Attorney General's office or a consumer law attorney, particularly given the pending litigation referenced above.
What's a safer alternative to Greenline Loans?
A federal credit union Payday Alternative Loan (PAL) is usually the lowest-cost option if you qualify, with APR capped well below what any tribal or payday-style lender can charge. State-licensed bad-credit installment lenders are a second option with meaningfully lower rates and full state oversight.