Ideal Credit Card Cashback Offers for Online Shopping and Travel (2026)
If you shop online regularly or travel even a few times a year, the right credit card can quietly put thousands of rupees back in your pocket — without any extra effort. The challenge is that there are hundreds of cards in India today, all promising "the best cashback," and most of them are designed to confuse rather than help you decide.
This guide cuts through that noise. We've mapped out the ideal credit card cashback offers for online shopping and travel in India in 2026 — which cards genuinely reward you, how much you actually earn, and which card fits which spending pattern. Whether you're an everyday Amazon shopper, a frequent flyer, or someone who does both, there's a setup here that works.
Why Cashback Cards Beat Reward Points for Most People
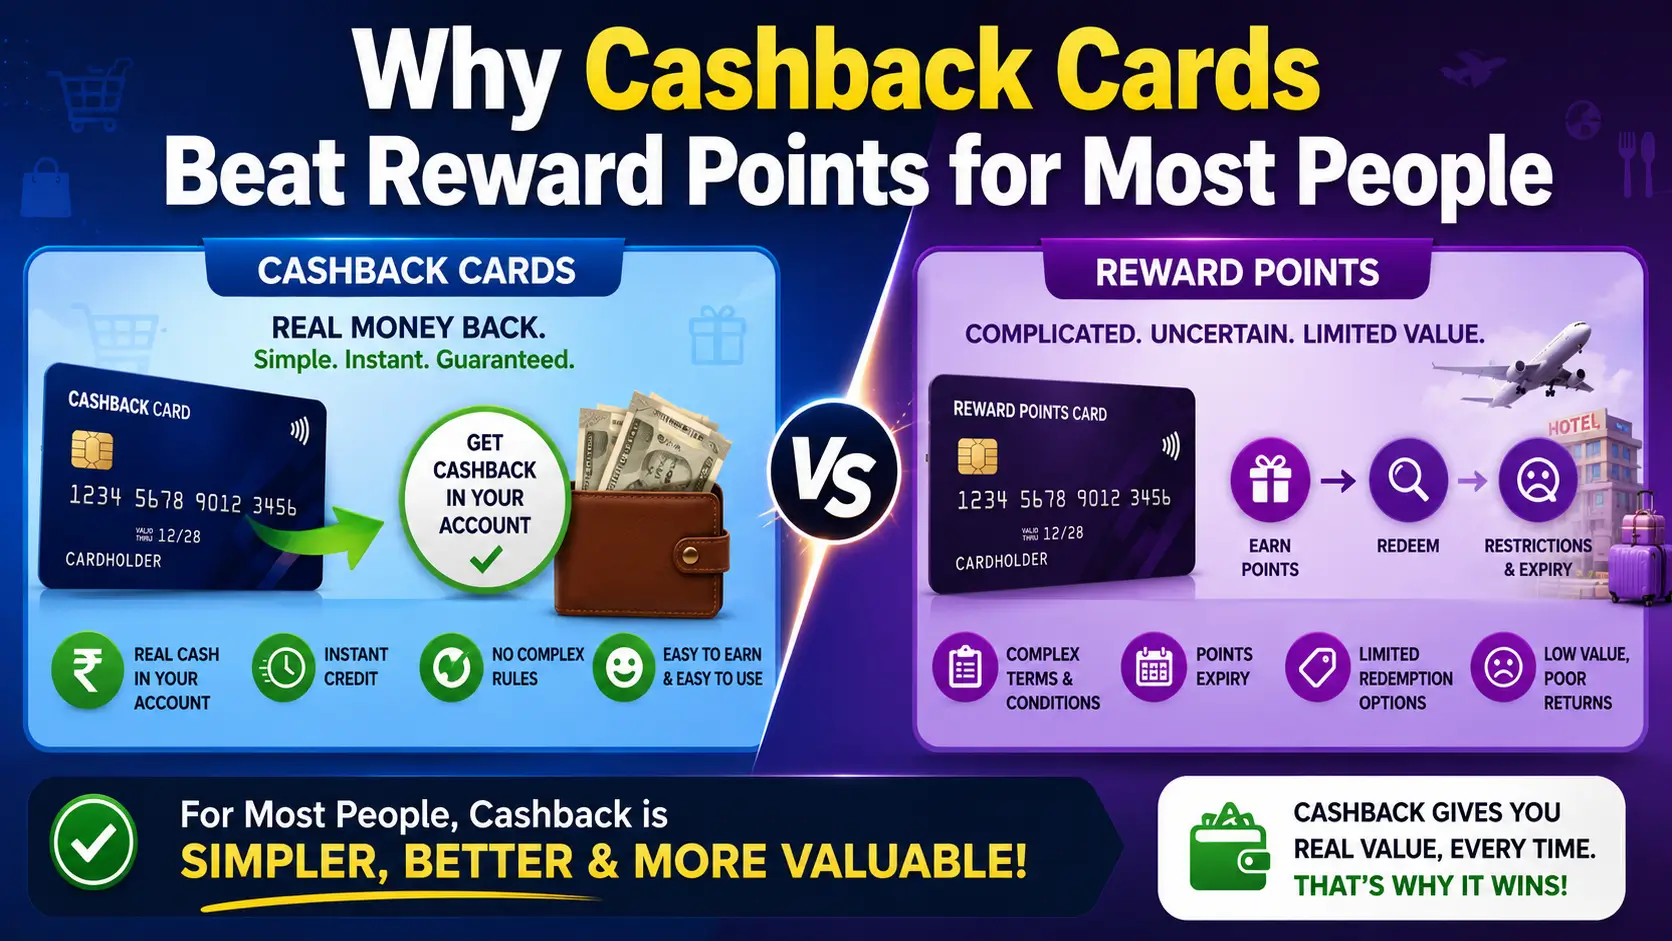
Reward points sound attractive until you try to redeem them. Expiry dates, low conversion ratios, restricted redemption categories, and devaluations can wipe out months of accumulated value overnight. Cashback, by contrast, is straightforward: you spend, you earn, the money hits your statement.
As one credit card analyst community summarized the 2026 landscape: cashback has become "the most stable reward currency" — ₹1 cashback is always ₹1, unlike air miles that can be devalued overnight. That stability, combined with the boom in digital spending across India, has made cashback cards the default smart choice for the majority of cardholders who aren't high-frequency flyers.
That said, for people who fly 8–10+ times a year, travel-specific miles cards often beat straight cashback in total value. We cover both below.
Best Credit Cards for Online Shopping Cashback
1. SBI Cashback Credit Card — Best Flat-Rate Online Cashback
Annual Fee: ₹999 (waived on ₹2 lakh annual spend) Best for: Heavy online shoppers who spread purchases across platforms
The SBI Cashback Card has held its ground as India's most straightforward online shopping cashback card. You earn 5% cashback on all online purchases, regardless of which platform or merchant — Amazon, Flipkart, Myntra, Zomato, or any other site. Offline transactions earn 1%.
The catch: cashback on online and offline spends combined is capped at ₹5,000 per month, which means the card is best optimized by those spending up to ₹1 lakh per month online. Beyond that ceiling, you're leaving money on the table.
Why it stands out: Most cards tie higher cashback to specific merchants. The SBI Cashback Card's merchant-agnostic 5% rate means you don't have to shop strategically — everything online earns equally.
2. Amazon Pay ICICI Credit Card — Best for Amazon Loyalists
Annual Fee: Nil (lifetime free) Best for: Amazon Prime members who spend significantly on the platform
For Prime members, this card offers 5% cashback on Amazon.in purchases — with no annual fee. Non-Prime members earn 3% on Amazon and 1% elsewhere. There's also 2% back on payments via Amazon Pay at partner merchants.
It's a no-brainer as a companion card. Since it's free for life, keeping it active costs nothing, and if Amazon is your default shopping destination, the 5% rate compounds meaningfully over a year.
3. Flipkart Axis Bank Credit Card — Best for Flipkart + Lifestyle Spends
Annual Fee: ₹500 Best for: Flipkart shoppers who also use Uber, Swiggy, and Cleartrip
This card offers 5% unlimited cashback on Flipkart and Cleartrip, plus 4% on preferred merchants including Uber, Swiggy, and Cult.fit, and 1.5% on everything else. The inclusion of Cleartrip effectively makes this a shopping-plus-domestic-travel card, and the 1% forex markup is notably low for a card at this price point.
The combination of high-frequency platforms — shopping, travel, food delivery — in one card makes it unusually practical.
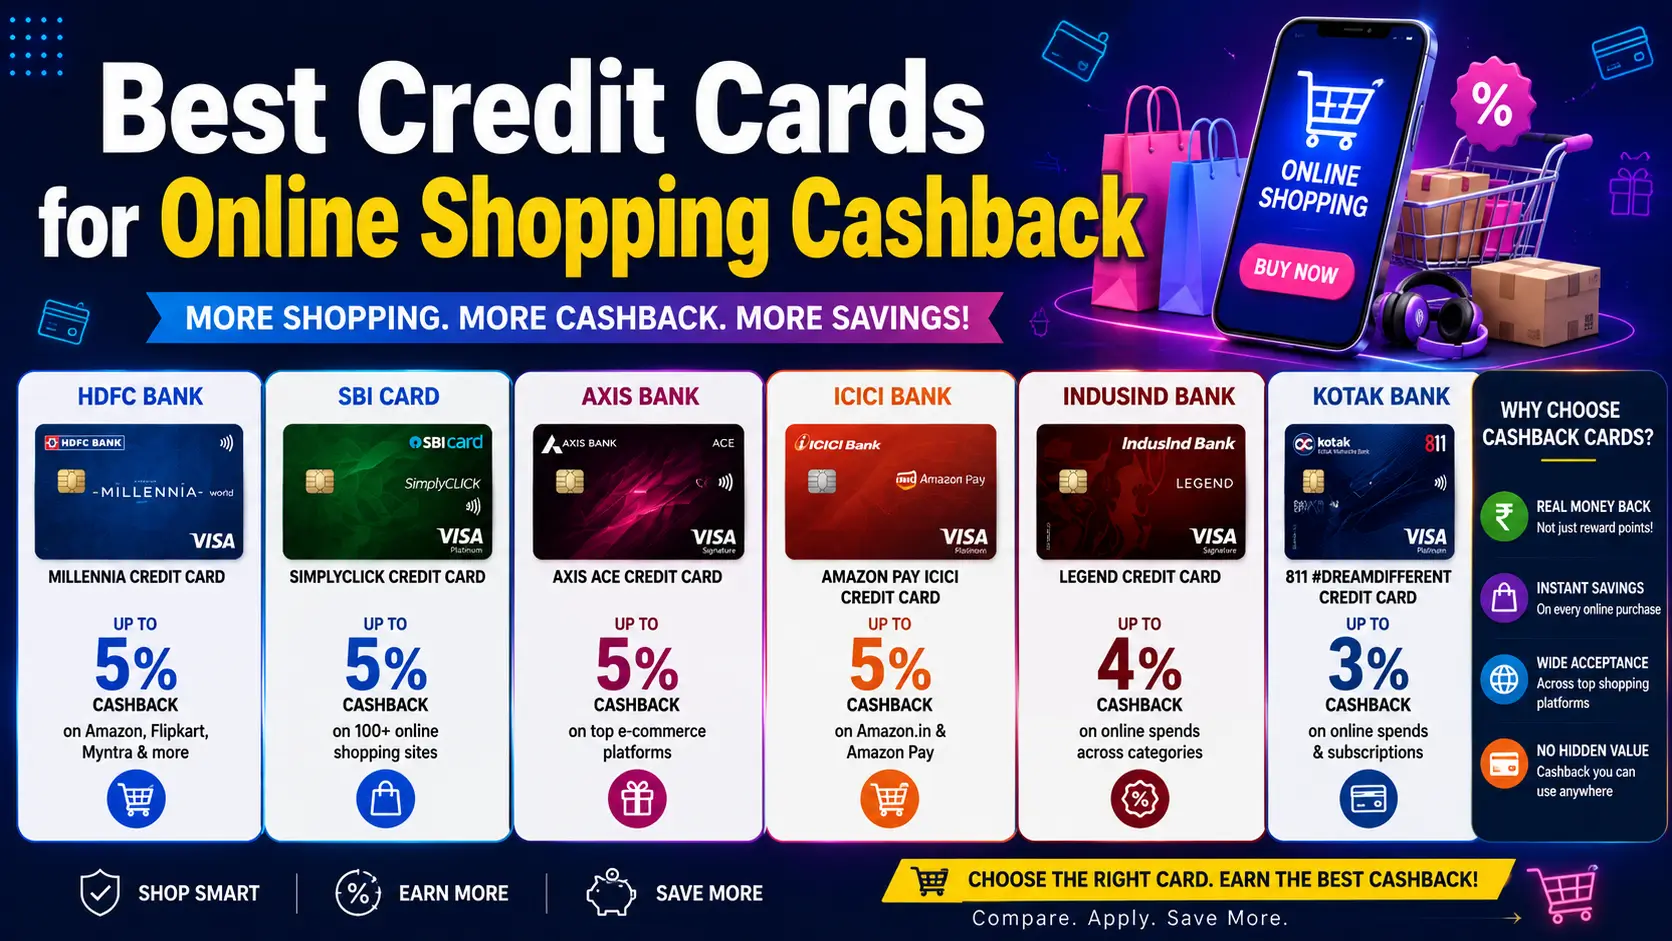
4. HDFC Bank Millennia Credit Card — Best for Multi-Platform Shoppers
Annual Fee: ₹1,000 (waived on ₹1 lakh annual spend) Best for: Millennials and Gen Z who shop across multiple e-commerce platforms
The HDFC Millennia earns 5% cashback on Amazon, Flipkart, Myntra, Zomato, and other major platforms, with 2.5% on PayZapp/SmartBuy and 1% on all other transactions. There's also up to 20% discount at select restaurants through Swiggy Dineout, which adds lifestyle value beyond shopping.
It's a solid all-rounder for the demographic that regularly splits spending across multiple apps rather than staying loyal to one platform.
5. HSBC Live+ Credit Card — Best for Groceries and Food Delivery
Annual Fee: ₹999 Best for: Those who spend heavily on groceries, dining, and food delivery
HSBC Live+ leads with 10% cashback on groceries, dining, and food delivery (capped at ₹1,000 per month), and 1.5% unlimited cashback on all other spends. If a significant chunk of your monthly spending is on BigBasket, Swiggy, Zomato, and restaurant visits, this card's accelerated category rate delivers strong returns.
Best Credit Cards for Travel Cashback and Miles
6. HDFC Bank Infinia Credit Card — Best Premium Travel Card (Invite Only)
Annual Fee: ₹12,500 (waived on ₹10 lakh annual spend) Best for: High-net-worth frequent flyers spending ₹10 lakh+ annually
The HDFC Infinia is widely regarded as India's most rewarding premium card for travelers. It earns 5 reward points per ₹150 spent, and on the HDFC SmartBuy portal, the multiplier climbs up to 10X — translating into an effective return of up to 33% on travel bookings. The card includes unlimited complimentary domestic and international lounge access via Priority Pass (1,000+ lounges globally) for both primary and add-on cardholders.
It's invite-only and aimed squarely at high spenders. For the right profile, it's unmatched.
7. Axis Bank Magnus Credit Card — Best for High-Spend Travelers
Annual Fee: ₹12,500 Best for: Frequent business and leisure travelers with significant monthly spend
The Axis Magnus pairs a strong base reward rate with unlimited domestic and international lounge access, low forex markup, and excellent airline/hotel transfer partners. It's the closest competitor to HDFC Infinia and the recommended choice for those who prefer Axis Bank's points ecosystem.
8. Axis Bank Atlas Credit Card — Best Mid-Tier Miles Card
Annual Fee: ₹5,000 Best for: Frequent travelers who want airline and hotel transfers without a super-premium fee
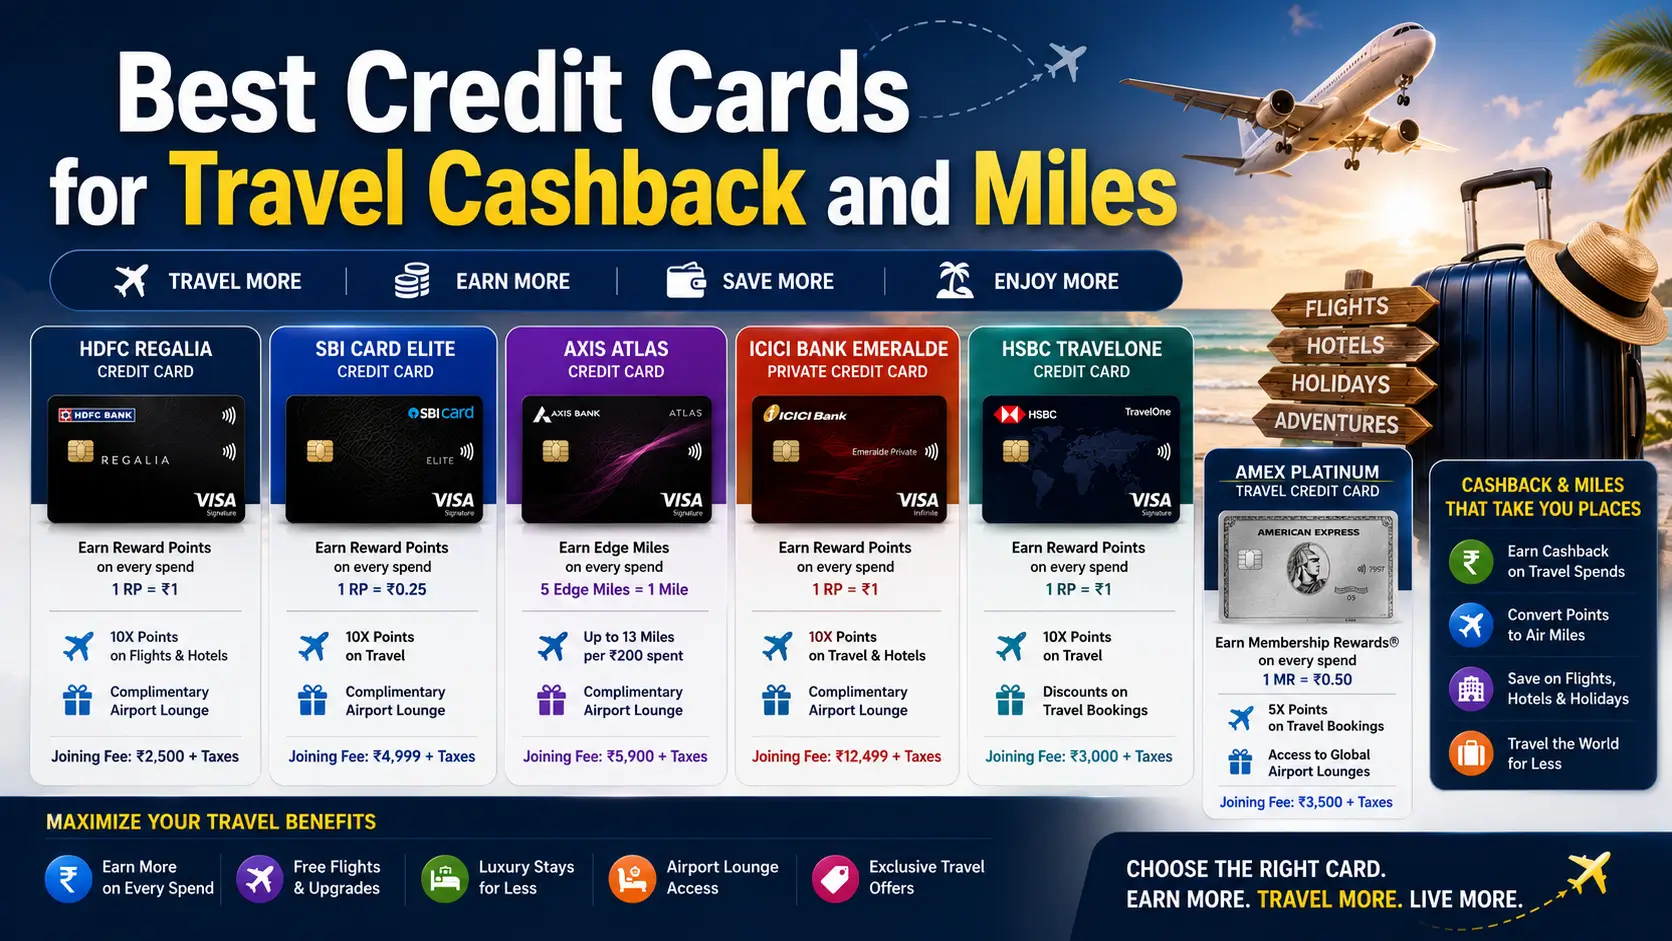
The Axis Atlas operates on a tier-based system — Silver (₹3 lakh annual spend), Gold (₹7.5 lakh), and Platinum (₹15 lakh) — and earns EDGE Miles that can be transferred to airline loyalty programs at a 1:2 ratio. It delivers 5% value back on travel spends and 2% on everything else. Lounge access scales with tier: 8 domestic visits at Silver, up to 18 at Platinum.
The miles transfer ratio and tier-based acceleration make it one of the most rewarding mid-premium travel cards currently available.
9. Federal Bank Scapia Credit Card — Best Free Travel Card
Annual Fee: Nil (lifetime free) Best for: Budget travelers who want lounge access without annual fees
Scapia is an outlier in the travel card space — zero annual fee, yet it includes unlimited domestic lounge access (with a minimum monthly spend of ₹10,000 on Visa). The reward rate is 10% on travel bookings via the Scapia app and 5% on UPI transactions. Scapia Coins can be redeemed directly for flights, hotels, and buses with no caps on redemption.
For someone who travels a handful of times a year and doesn't want to commit to an annual fee, Scapia is the most accessible entry point into travel card benefits.
10. Axis Bank Horizon Credit Card — Best Airline-Agnostic Miles Card
Annual Fee: ₹3,000 Best for: Frequent travelers who don't want to be locked into one airline
Unlike co-branded airline cards, Axis Horizon earns flexible EDGE Miles (5% value back on travel, 2% on other spends) that transfer to multiple airline and hotel partners. It also offers a notably high number of complimentary domestic lounge visits — up to 8 per quarter on the Visa variant — without spending-based conditions attached.
Cards That Cover Both: Online Shopping + Travel
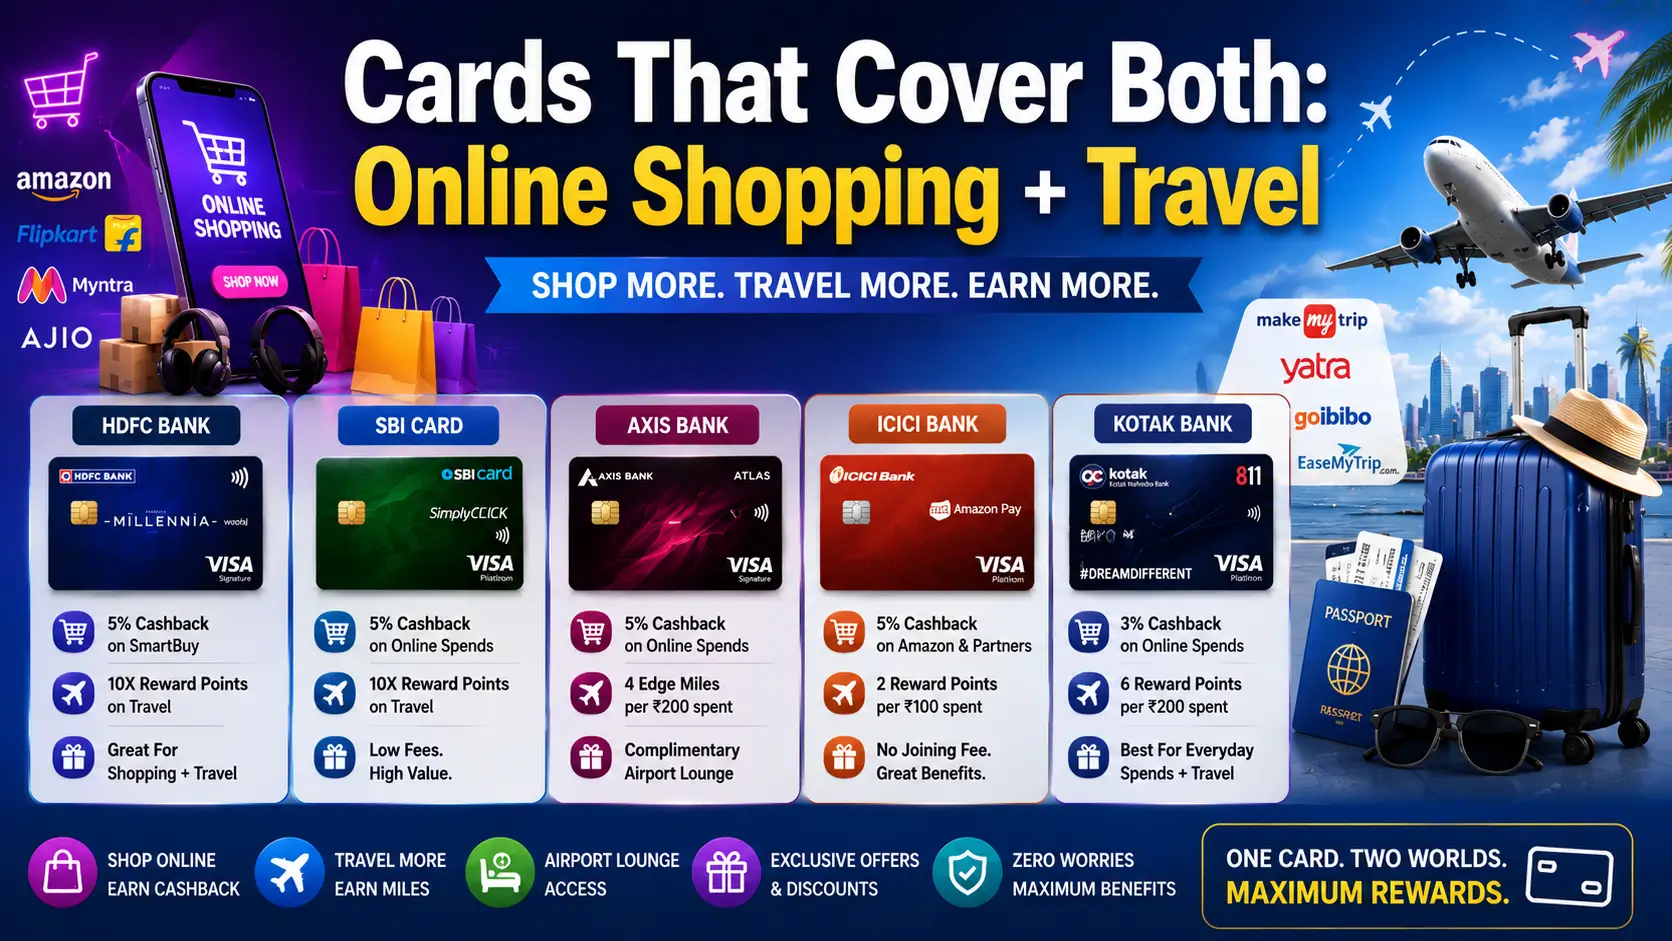
The smartest setup for most people isn't one card — it's a combination. But if you want a single card that handles both categories well:
HDFC Regalia Gold Credit Card
Annual Fee: ₹2,500 The Regalia Gold offers a reward rate of 1.3–13% depending on the category, Priority Pass membership (shared across primary and add-on cardholders), and partnership discounts on MakeMyTrip, Club Mahindra, and other travel platforms. It bridges the gap between an everyday shopping card and a travel card without the premium fee of Infinia or Magnus.
Tata Neu Infinity HDFC Bank Credit Card
Annual Fee: ₹1,499 For households in the Tata ecosystem (BigBasket, Air India, 1mg, Croma, Westside), this card delivers up to 10% back as NeuCoins on Tata Neu app spends, domestic and international lounge access, and accelerated rewards on Air India bookings. If you're already a Tata platform user, the compounding ecosystem rewards make this card exceptional value.
How to Choose the Right Card for Your Spending
There's no single best card — it depends on where your money actually goes. Here's a simple framework:
If your primary spend is online shopping:
- Spread across platforms → SBI Cashback Card (5% flat, merchant-agnostic)
- Mostly Amazon → Amazon Pay ICICI (free, 5% for Prime members)
- Mostly Flipkart → Flipkart Axis (5% + lifestyle partners)
If you travel 4–8 times a year (domestic focus):
- No annual fee preference → Scapia (free, unlimited lounge)
- Mid-budget → Axis Horizon (₹3,000, high lounge access, flexible miles)
- More travel spend → Axis Atlas (₹5,000, tier-based acceleration)
If you travel 10+ times a year internationally:
- High spender (₹10 lakh+/year) → HDFC Infinia (unlimited lounge, 33% on SmartBuy)
- Axis ecosystem preference → Axis Magnus
If you want one card for both:
- ₹2,500 budget → HDFC Regalia Gold
- Tata platform user → Tata Neu Infinity HDFC
Annual fee consideration: Always calculate whether the cashback and benefits you'll realistically earn outweigh the annual fee. Many cards waive fees above a spending threshold — factor that in before dismissing a card for its cost.
Watch Out For: Cashback Caps and Common Traps
Even the best cards have limits. Here are the most common ways cardholders lose value without realizing it:
Monthly and quarterly caps: The SBI Cashback Card caps returns at ₹5,000/month. HSBC Live+ caps the 10% grocery/dining cashback at ₹1,000/month. If you're a high spender, these ceilings mean you need a second card for overflow spend.
Milestone-based lounge access: Several cards that advertise lounge access have shifted to spend-based conditions. For example, some cards require ₹35,000–₹50,000 in quarterly spend to unlock their quarterly lounge visits. Read the fine print before assuming access is unconditional.
Category exclusions: Most cards exclude fuel, rent, utility bill payments, insurance premiums, and cash withdrawals from cashback calculations. These are often the largest monthly expenses for many households.
Interest charges negate cashback: Carrying a balance means paying 30–45% annualized interest, which will outpace any cashback earned. These cards only make financial sense if you pay the full statement balance every month.
Devaluations: Travel cards with miles programs are subject to devaluations — airlines and banks can change point values with limited notice. Axis Atlas and several other cards saw their partner rosters change in 2024–25. If you're accumulating miles for a specific redemption, plan your timeline carefully.
How to Stack Cards for Maximum Returns
The most effective way to maximize cashback is to use two or three cards strategically:
Combination 1 — Entry level (₹0–₹1,500 total annual fees):
- Amazon Pay ICICI (free) for all Amazon spends
- Scapia (free) for travel bookings and lounge access
- SBI Cashback (₹999) for everything else online
Combination 2 — Mid-tier (₹1,500–₹5,000 total annual fees):
- SBI Cashback for flat 5% online
- Flipkart Axis for Flipkart/Cleartrip/food delivery
- Axis Horizon for travel bookings and lounge access
Combination 3 — Premium (₹10,000+ total annual fees):
- HDFC Infinia or Axis Magnus for high-value travel redemptions and lounge access
- HSBC Live+ for groceries and dining cashback
- Amazon Pay ICICI as a zero-fee online shopping backup
The key principle: route each spending category to the card with the highest rate for that category. Don't let every transaction default to one card.
Frequently Asked Questions (FAQs)
Which credit card gives the highest cashback on online shopping in India?
The SBI Cashback Credit Card offers 5% flat cashback on all online purchases with no merchant restrictions, making it the highest flat-rate online cashback card. For Amazon-specific purchases, Amazon Pay ICICI's 5% for Prime members on a lifetime-free card is equally competitive.
Are there credit cards with both cashback and airport lounge access?
Yes. The Flipkart Axis Bank Credit Card (₹500 annual fee) includes some lounge benefits. The HDFC Millennia and Regalia Gold both offer lounge access alongside shopping rewards. For a free card with unlimited lounge access, Federal Bank Scapia is the strongest option.
What is the best credit card for international travel in India?
For high spenders, HDFC Infinia and Axis Magnus offer unlimited international lounge access, low effective forex markup, and strong miles transfer programs. For moderate spenders, the HSBC Travel One or Axis Horizon offer good value with more accessible annual fees.
Is the SBI Cashback Credit Card worth it for online shoppers?
Yes, for most online shoppers spending ₹10,000–₹1,00,000 per month online. The 5% merchant-agnostic cashback is the highest flat rate available without merchant restrictions, and the ₹999 annual fee is waived at ₹2 lakh annual spend — effectively making it free for regular users.
Can I use a cashback credit card for travel bookings?
Yes — the SBI Cashback Card earns 5% on online travel bookings too, since travel platforms like MakeMyTrip and Cleartrip qualify as online transactions. However, dedicated travel cards (Axis Atlas, HDFC Infinia) typically offer better value for frequent travelers through miles transfers and lounge access.
What is the minimum spend to unlock lounge access on most cards?
It varies significantly. Some cards like Scapia and Axis Horizon offer lounge access without spend conditions. Others require ₹35,000–₹50,000 quarterly spend. Always check the specific terms of your card rather than assuming access is automatic.
Should I prefer cashback or reward points?
For most people, cashback is simpler and more reliable — ₹1 is always ₹1. Reward points deliver higher theoretical value but require active management, have expiry risks, and are vulnerable to devaluations. Unless you're flying 10+ times a year and optimizing for specific airline or hotel redemptions, cashback is the practical choice.
Final Take
The ideal credit card for online shopping and travel cashback in India in 2026 doesn't exist as a single card — it exists as a combination tuned to your actual spending. For most people, a free or low-fee card covering online shopping (SBI Cashback or Amazon Pay ICICI) paired with a travel card covering lounge access and flight bookings (Scapia or Axis Horizon) covers 90% of use cases at minimal cost.
Before applying for any card, run the numbers against your last three months of bank statements. Calculate what you would have earned on each card with your real spending. The card with the best marketing is rarely the card that puts the most money back in your pocket.
Disclaimer: Credit card features, fees, and cashback rates are subject to change. Verify current terms with the respective issuer before applying. This article is for informational purposes only and does not constitute financial advice.